How AI Is Changing the Way San Antonio Buyers Search for HomesIf you’re thinking about buying a home in San Antonio, chances are you’ve already used the internet to start your search.

Dated: May 25 2020
Views: 755
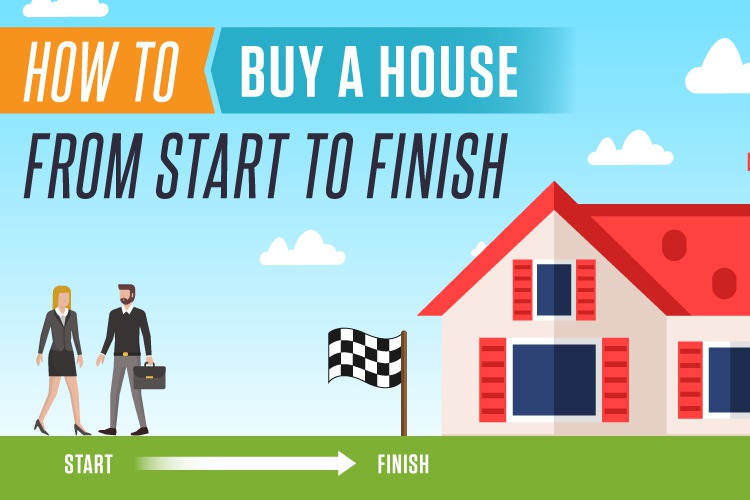
If you're new to the homebuying process, or if it's just been a while, then the thought of mortgages, inspections, and house hunting can be a little intimidating. However, as long as you know what to expect, it doesn't need to be. So here's a quick guide that can help you through each step of the process, from first thinking about buying a home to closing the deal.
1. Check your credit and strengthen it if necessary
You can obtain a conventional loan with a 620 FICO score, but that doesn't make it a good idea. According to recent data from myFICO.com, someone with the minimal credit score can expect to pay over $82,000 more in interest over the life of a $250,000, 30-year mortgage than a top-tier (760-plus) borrower.
So, before you even start the home buying process, check your own credit. Make sure you use an actual FICO score, as this is what most lenders see. Doing this first will give you plenty of time to work on your credit score if necessary. A small increase can make a big difference in the long run, so here are a few suggestions if you need to do a little damage control.
2. Decide on a reasonable budget
It's possible to obtain a mortgage whose payment makes your total monthly debts 45% of your pre-tax income, but by no means should most people spend this much. Depending on your tax bracket, 45% of your pre-tax income could be almost all of your after-tax income, and this doesn't leave much for anything else. In order to prepare for a budgeting discussion, here's a link to an in-depth article that can help you figure out how much you should realistically spend on your home.
3. Research mortgage options
There are several types of mortgages available. Conventional loans are the most common, and they require a 3% to 20% down payment. Remember that many loan issuers will require you to pay private mortgage insurance if you fail to provide a 20% down payment. There are also FHA loans with low down payment requirements and easier credit standards than conventional loans, VA loans for qualified current and former military personnel, and USDA loans for borrowers in certain rural areas (the latter two don't require a down payment at all). In addition, many banks have their own loan programs, so it's a good idea to do a little research.
4. Figure out where your down payment and closing costs will come from
Once you decide which mortgage type is right for you, you'll need to figure out when your down payment is going to come from. Some types of mortgages allow some or all of the down payment to come from a gift, while others are more restrictive. In addition, plan on spending in the range of 1%-3% of the home's price for closing costs. Plus, most lenders want to see that you have enough money in reserves (this can be in retirement accounts) to cover your mortgage payments for a few months.
5. Gather your documentation
When you apply for a mortgage, the lender will ask you for lots of documentation. By gathering it all ahead of time, you can help expedite the process, and obtain your approval faster. To help you get started, you should plan to need the following documents when applying:
Keep in mind that this isn't a complete list, and your lender may ask for more information.
6. Get a preapproval
A mortgage preapproval is essentially the same thing as applying for a mortgage, just without a specific home in mind. In order to obtain a preapproval, a lender needs to check your credit, verify your income and employment status, and may need to see other documentation as well. Keep in mind that this is different from a pre-qualification, which is based on unverified information you provide and won't carry nearly as much weight when shopping for a home. A preapproval is a commitment to lend you money and makes you look like a much more serious buyer.
7. Hire a real estate agent
Technically, this one is an optional step. You can buy a home without a real estate professional, but there are a few reasons not to do so. First, the real estate agent will do all of the research, contracts, and other time-consuming parts of the home buying process for you -- preventing your home search from turning into a full-time job. Additionally, a good real estate agent will have an extensive knowledge of the local market and can guide you through the entire process from looking at houses to sitting down at the closing table.
Your real estate agent has your back whether you're a buyer or a seller. Agents have what's known as a "fiduciary" responsibility to their clients. They legally obligated to put their clients' best interests first.
You might not be a negotiation shark if you don't happen to be an attorney, mediator, union rep...or a real estate agent. Remember that fiduciary responsibility your agent has to you. It's your agent's job to get you the best possible price for your home or to see to it that you get the best possible deal on the property you want to buy.
Agents are trained to negotiate well, if only from experience. They know what normally works and what does not. Most have tried-and-true techniques all their own. And, most importantly, they have no emotional stake in the outcome that can cloud their thinking.
You, on the other hand, might be willing to come up with $10,000 more to purchase that to-die-for home, never realizing that it's really not necessary because you possess certain bargaining chips. It's just more money saved if you have an agent who prevents you from taking an unnecessary financial plunge.
You might be far out of your element when it comes to reviewing and understanding the multiple documents involved in a real estate deal, and you should have a thorough understanding of what you're getting into regardless of whether you're buying or selling. Purchase agreements alone can top 10 pages in 2019, not to mention federal, state, and local document requirements.
Luckily, your agent will be far more familiar with all this paperwork than you are. Consider this if you're still thinking about saving money: Some mistakes or omissions in these documents can cost you as much as that commission you were trying to avoid paying—or even far more.
Here's an example: Maybe a buyer makes an offer on a home, but it's contingent on getting a mortgage. There's no possibility that the buyer could purchase the property without first securing financing—but there's no such contingency or escape hatch built into the purchase agreement to let the buyer out of the deal if financing fails. The buyer is obligated to go through with the sale or be sued if it turns out that a mortgage isn't happening.
Your agent will be alert for issues that might not cross your mind, such as furnace issues, leaks, roofing problems, and mold and insect issues. An agent will recognize the telltale signs of these problems and know how best to approach them. Again, this experience and knowledge can end up saving you thousands down the road.
You know exactly how much you want for your home if you're the seller, but is the price you've arrived at reasonable? You might only know for sure if you're able to identify comparable sales that confirm that you're in the right range—or not. Agents can do comparative market analyses in their sleep.
An agent can hand over-researched, current, and reputable data regarding a neighborhood's demographics, crime rates, schools, and other important factors. That's a lot of time-consuming research to do on your own, particularly if you don't know where to start.
Consider hiring a broker for a smaller one-time fee to simply review your contracts before signing if you're still dead set against hiring an agent to take care of all this.
8. Look at houses
This is the fun part. Once you've narrowed it down to the neighborhoods you like, the best advice I can give is to make a list of what you have to have and things you simply want. Walk away from properties that don't have the things on your must-have list, but it is silly to lose an otherwise perfect home for easily fixable cosmetic issues.
9. Make an offer
When it comes to offers, it's important to appear to be a serious buyer, while still trying to get the best deal possible. As I mentioned before, this is something your real estate professional can help you with, as there are a lot of variables that go into making an offer. Is the home overpriced or priced correctly? Is your local market a buyer's market or seller's market? And how long has the home been sitting on the market?
10. Get an inspection and wait for the closing day
After the seller accepts your offer, you generally have a short inspection period (three to five days is common). During this time, you have the option, but not the obligation, to hire a professional to do a thorough inspection of the property. However, the inspection is a must-do. The last thing you want is to move into a house only to find out that the supposedly new HVAC is really 30 years old, the home has structural issues (like a load-bearing wall was inadvertently removed at some point), or that the entire electrical system isn't up to code and is unsafe. All three of these have actually come up during my own home searches -- and the home inspections revealed them and gave me an "out."
One of the most common questions I get asked by homebuying friends is "Why does it take so long to close on a home?" And the short answer is that it often has little to do with you or the seller -- the mortgage and legal processes simply take a long time. Chances are that after the contracts are signed, you'll still have a month or more to wait before you actually get the keys. This can be a stressful time, but as long as you follow your mortgage processor's instructions in a timely manner, the finish line should be within reach.
Selling or buying a home is a big decision and a long process. It is important to have someone you can turn to and ask questions of. I would like to earn the right to be that person.
Please feel free to reach out to me. It is a good idea to have someone on your side when purchasing a home. Here is my contact information, in case you misplaced it?
Yamel Romano, Associate Broker
RE/MAX Realty Advantage
(210) 404-5590 Cell
(210) 495-5252 Office
Facebook:@YamelRomanoSanAntonioRealtor
As a Real Estate agent, I’m professional, honest, and very dedicated to helping my clients find the home of their dreams. Whether you are buying or selling a home or just curious about the local....
How AI Is Changing the Way San Antonio Buyers Search for HomesIf you’re thinking about buying a home in San Antonio, chances are you’ve already used the internet to start your search.
Looking for walkable streets, rich local culture, vibrant coffee spots, and a strong sense of community in San Antonio? Here are 5 neighborhoods generating huge buzz right now.1. Pearl & Tobin
📅🏡 Planning Your 2026 Real Estate Moves?We just released a full guide to the best buying and selling seasons in San Antonio!Read the blog here ➡️ https://www.buyselllovesanantonio.com
🚨 Don’t get caught in a real estate scam! From fake listings to wire fraud, these schemes are more common than you think.🧠 Stay one step ahead and protect your money — read our
 Information provided courtesy of LERA MLS. IDX information is provided exclusively for consumers' personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information is believed to be accurate but not guaranteed. Provided courtesy of LERA MLS. Copyright 2026 LERA MLS, All Rights Reserved. Data last updated September 21, 2026 6:07 AM UTC
